Should a Teacher Buy Service Credit? A Decision Process for Prior Service, Leave, and Out-of-State Years
Evaluate a teacher service-credit purchase by verifying eligibility, cost, benefit impact, deadlines, and whether the same service is credited elsewhere.
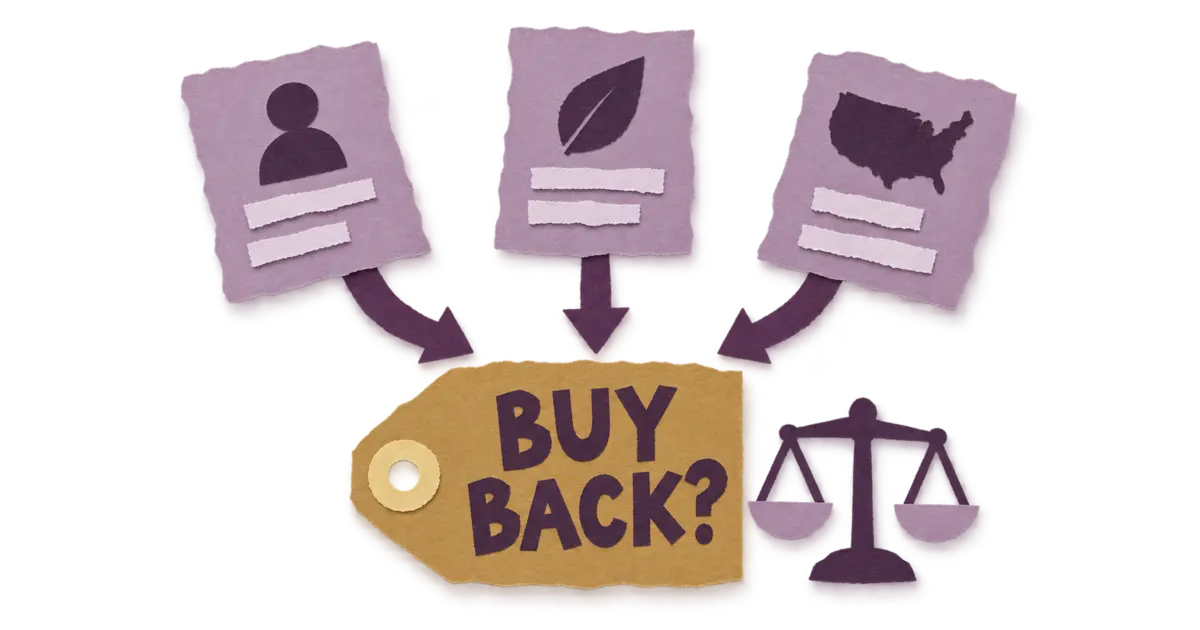
“Buy the years” sounds simple until the retirement system produces a cost statement. A service-credit purchase can increase a future pension or help with eligibility in some plans, but eligible service, pricing, deadlines, and benefit effects are system-specific. The right question is not whether service credit is generally good. It is what one additional unit of credit does inside your formula at your cost.
Identify the service category before asking for a price
Retirement systems often distinguish among refunded service, out-of-state teaching, substitute service, military service, approved leave, and other categories. Texas TRS, for example, publishes separate eligibility and cost rules for several types of purchasable credit. CalSTRS also identifies specific past employment and approved leaves that may qualify.
Start with the exact service you want recognized: school district, dates, full- or part-time status, whether you contributed to another retirement plan, and whether you later took a refund.
Do not assume the same years can produce two full public pensions
Some systems restrict purchases when the same service is maintained for a benefit in another public retirement system. New York State Teachers' Retirement System, for example, places conditions on prior-service credit where the member is entitled to another public retirement benefit for that service. The details vary, so disclose the other system rather than assuming you can preserve both credits unchanged.
Ask for an official cost statement
Online examples are not enough. Purchase cost can depend on age, compensation, actuarial assumptions, interest, or the type of service. CalSTRS notes that contribution rates for certain purchases are age-based and that rates can change. Texas uses different cost methods by service category.
Get the plan's current calculation for your record, along with the date through which it is valid. If the quote grows with interest or age, note that explicitly.
Measure the benefit change in dollars, not just years
Run the retirement estimate with and without the purchase if the system provides that functionality. Suppose a purchase costs $28,000. The meaningful comparison is not “I gain two years.” It is how those two years change monthly pension, retirement eligibility date, survivor options, or another formula threshold.
If the purchase moves you across an eligibility or vesting milestone, its value can be very different from a purchase that only increases the monthly formula slightly.
Separate “helps eligibility” from “increases the benefit”
Some credit types count toward the pension amount but not every eligibility threshold, or vice versa. Read the plan description for the specific service type. Avoid applying rules from another purchase category to yours.
- Identify service typeCheck whether the plan accepts this category and whether it overlaps another system.
- Request an official quoteUse the plan’s record-specific cost statement and validity date.
- Model with and without itCompare benefit and any eligibility effect.
- Check the deadlineConfirm whether retirement or another status change closes the purchase window.
- Choose the payment pathReview taxes and paperwork for the permitted method.
Compare the purchase with keeping the money invested elsewhere
A service purchase uses real cash, rollover funds, or payroll deductions that could otherwise remain in savings or another retirement account. Compare the expected pension increase with the loss of liquidity and investment opportunity. This is where a financial planner familiar with public pensions can be useful, especially for a large purchase close to retirement.
Do not assume the pension purchase wins because the benefit is “guaranteed,” and do not assume investing wins because the account stays liquid. The trade-off depends on cost, formula, age, tax treatment, survivor needs, and how long the pension is expected to be paid.
Check the deadline against your career plan
Some purchases must be completed before retirement or another status change. Texas TRS publishes deadlines by purchase type and notes that purchases needed for retirement eligibility must be completed by the effective retirement date. If you are changing states, taking a refund, or retiring soon, ask whether those actions close the purchase window.
Verify how payment method affects taxes and paperwork
Plans may allow direct payment, rollovers from eligible retirement accounts, or payroll installments. Each method can have tax and administrative consequences. Use the retirement system's instructions and, for tax questions, qualified tax advice rather than improvising a rollover.
Use a break-even calculation carefully
A rough break-even period can be useful: purchase cost divided by the estimated annual increase in pension. If a $24,000 purchase raises the annual benefit by $3,000, the simple break-even is eight years of benefit payments. But that ignores taxes, cost-of-living adjustments, survivor elections, time value of money, and the possibility that the credit changes retirement eligibility. Treat it as one lens, not a final answer.
Document why you bought—or declined
Save the service verification, official quote, benefit estimates, deadline, and the assumptions you used. If you decline now because the cost is too high, record whether the quote is expected to rise; you may want to revisit the decision if your retirement date or salary changes.
Service-credit purchases are among the most plan-specific decisions in a teacher career. A careful decision starts with the retirement system's own records, not with a colleague's cost or a generic “buyback is worth it” rule.
The article’s simple cost-to-benefit calculation excludes taxes, survivor choices, time value, and eligibility effects. Use the plan’s own estimates and assumptions.
Ask for a written quote and scenario comparison
Request the plan’s official purchase estimate for the exact service type and confirm the quote’s expiration date, eligible payment methods, installment rules, and deadline relative to retirement. Ask whether the purchased credit counts toward vesting, benefit calculation, eligibility, or only some of those purposes. Request estimates with and without the purchase using the same planned retirement date and survivor option; otherwise the comparison can be misleading. Keep taxes, investment returns, inflation, health coverage, and the possibility of leaving the system in mind, but do not assume any one of these makes a purchase worthwhile. If the decision is large, consider a qualified financial professional familiar with public pensions. Save the estimate and your assumptions so you can revisit the choice if your salary, service record, or retirement timing changes.
Check whether the purchase is reversible
Ask the plan whether a submitted purchase can be canceled, refunded, or rolled over if you leave before retirement, and what fees or tax reporting may apply. Do not assume that a payment can be recovered on the same terms as ordinary employee contributions. Put the plan’s answer next to your quote and confirm it applies to the exact service type being considered.
Sources checked
Questions teachers ask
Can every teacher buy out-of-state service credit?
No. Eligibility, limits, cost, and treatment of service credited in another system vary by plan.
Is the quoted purchase cost permanent?
Not necessarily. Some systems use age, interest, compensation, or changing contribution rates, so a cost statement may have an expiration or increase over time.
Does purchased service always let me retire earlier?
No. A credit type may increase the benefit without satisfying every retirement-eligibility rule. Check the specific plan provision.
How do I compare a purchase with investing the same money?
Compare the official pension increase and any eligibility effect with the purchase cost, liquidity you give up, taxes, survivor needs, and alternative investment assumptions.